Days Inventory Outstanding (DIO)
The Days Inventory Outstanding (DIO) is the number of days it takes on average before a company needs to replace its inventory.
DIO is often measured to improve a company’s go-to-market, sales and marketing (S&M), and product pricing strategies based on historical customer demand and spending patterns.
In This Article
- Days inventory outstanding (DIO) measures the average number of days that a company retains its inventory on hand before selling it.
- The formula to calculate DIO starts with determining the average inventory balance and dividing that figure by cost of goods sold (COGS), and multiplying the result by the time period (usually 365 days).
- Conversely, the days inventory outstanding (DIO) can be calculated by dividing the number of days in a given period by the inventory turnover ratio.
- A lower days inventory outstanding (DIO) implies quicker inventory turnover and an efficient conversion strategy, contrary to a higher DIO ratio.
How to Calculate Days Inventory Outstanding?
DIO stands for “Days Inventory Outstanding”, and measures the number of days required for a company to sell off the amount of inventory it has on hand.
Therefore, companies are incentivized to minimize their days inventory outstanding (DIO) to reduce the time that inventory is sitting idly in their possession, since that implies its operating efficiency improved.
To calculate the days inventory outstanding (DIO) of a company, two inputs are necessary:
- Inventory Balance → On the balance sheet, the inventory line item represents the dollar value of the raw materials, work-in-progress goods (WIP), and finished goods of a company.
- Cost of Goods Sold (COGS) → On the income statement, the COGS line item represents the direct costs incurred by a company while selling its goods or services to generate revenue.
An increase in an operating working capital asset, such as inventory, represents an “outflow” of cash.
Hence, an increase in working capital – i.e. current operating assets minus current operating liabilities – causes a reduction in the free cash flow (FCF) of a company..
With that said, if the inventory balance of a company rises, that means more cash is tied up in the operations, since it is taking more time for the company to sell and cycle through its inventory compared to the time needed to produce it.
Days Inventory Outstanding Formula (DIO)
The formula to calculate days inventory outstanding (DIO) consists of dividing the average (or ending) inventory balance by cost of goods sold (COGS) and multiplying by 365 days.
Days Inventory Outstanding (DIO) = (Average Inventory ÷ Cost of Goods Sold) × 365 Days
Conversely, a different method to calculate DIO is to divide 365 days by the inventory turnover ratio.
Days Inventory Outstanding (DIO) = 365 Days ÷ Inventory Turnover
What is a Good Days Inventory Outstanding?
A comparative benchmarking analysis of a company’s inventory turnover and DIO relative to its industry peers provides useful insights into how well inventory is being managed.
The average inventory turnover and DIO varies by industry; however, a higher inventory turnover and lower DIO is typically preferred as it implies the management of inventory is closer to an optimal state.
In addition to being an indicator of ordering and inventory management efficiency, a high inventory turnover ratio and low DIO means higher free cash flows.
That is why the inventory turnover ratio and days inventory outstanding (DIO) are valuable metrics to track for companies, especially those selling physical products (e.g., retail, e-commerce).
- If the number of days it takes on average to clear out the inventory is high relative to comparable peers, there may not be enough demand for the product, the pricing might be too expensive, or it may be time to reconsider the target customer profile, etc.
- As a general rule of thumb, lower DIO is viewed more favorably since it implies the company is more efficient at selling its inventory (and is avoiding stock-piling inventory)
- The company may be failing to convert inventory into sales or is not managing inventory efficiently compared to others due to an ineffective marketing strategy where it fails to get enough exposure compared to others in its sector
- If a company has a low DIO, that means it is converting inventory into revenue more quickly – meaning more FCFs are available for reinvestments or other purposes like paying down debt
- Or in the worst-case scenario, the product may have become obsolete and substantial discounts would be required to get rid of the inventory (or incur an inventory write-down)
- One caveat is that companies with a low DIO might be overwhelmed if demand were to see a sudden increase; if inventory were to ever fall to zero, then the company would be missing out on potential sales
DIO vs. Inventory Turnover: What is the Difference?
The concept of inventory turnover is closely tied to days inventory outstanding (DIO), as inventory turnover refers to how often a company’s inventory balance needs to be replenished (i.e., “turned over”) each year.
For purposes of forecasting, inventory is ordinarily projected based on either inventory turnover or days inventory outstanding (DIO).
Since a higher turnover ratio means the company is selling off its inventory balance more frequently, companies strive to increase the turnover count to minimize the retention of existing inventory to avoid the build-up of unsellable/low-demand products.
If the inventory turnover is higher relative to comparable companies in the same industry, that is perceived as a positive sign in most cases, as it implies:
- Effective Customer Acquisition Strategies → The company is selling off its products quickly (i.e., demand-based ordering, “just-in-time”).
- High Market Demand → There is adequate customer demand in the market for the product being offered.
- Market-Based Pricing → The pricing of the product appears to be set around a reasonable range, which stems from understanding the target market(s) and customer profile.
In contrast, a low inventory turnover ratio indicates the company is struggling to sell its products – meaning, less free cash flows since more of the FCFs are tied up in operations and cannot be deployed for other purposes.
The inventory turnover ratio compares the cost of goods sold (COGS) incurred by a company to either the average (or ending) inventory balance.
Inventory Turnover Ratio = Cost of Goods Sold (COGS) ÷ Average Inventory
Note that the average between the beginning and ending inventory balance can be used for both the calculation of inventory turnover and DIO.
Why? The income statement covers a specific period, whereas the balance sheet is a snapshot at one particular point in time – thus, the average is used to prevent a timing mismatch between the numerator (an income statement item) and denominator (a balance sheet item).
However, in practice, the ending balance of inventory is often used for the convenience factor.
Unless the company operates in a highly seasonal industry with fluctuations in sales throughout the year, the difference between methodologies tends to be insignificant in most cases.
Days Inventory Outstanding Calculator (DIO)
We’ll now move on to a modeling exercise, which you can access by filling out the form below.
1. Income Statement Assumptions
Suppose we’re tasked with measuring the operating efficiency of a company, which reported a cost of goods sold (COGS) of $100mm and an inventory balance of $20mm in 2020.
Furthermore, the company’s COGS are expected to grow each year at a constant 5% growth rate year-over-year (YoY).
- Cost of Goods Sold (COGS) = $100 million
- Inventory = $20 million
- % COGS Growth – Step Function = +5% YoY
2. Inventory Turnover Ratio Calculation Analysis
Based on that information, we can calculate the inventory by dividing the $100mm in COGS by the $20mm in inventory to get 5.0x for the inventory turnover ratio in 2020.
The 5.0x inventory turnover ratio implies that, on average, the company goes through its inventory and must restock it five times per year.
- Inventory Turnover Ratio, 2020A = $100 million ÷ $20 million = 5.0x
3. Days Inventory Outstanding Calculation Example
Next, the company’s days inventory outstanding (DIO) can be calculated by dividing the $20mm in inventory by the $100mm in COGS and multiplying that by 365 days – which results in 73 days.
Therefore, the company requires roughly ~73 days to clear out its inventory, on average.
For purposes of simplicity, we are using the ending inventory balance in our formulas. But if you wanted to use the average inventory balance, it would just be the sum of the beginning and ending inventory balance divided by two.
In the next step, we will carry forward the inventory turnover assumption of 5.0x and the DIO assumption of 73 days to project future inventory levels.
- Inventory Turnover, 2020A = 5.0x
- Days Inventory Outstanding (DIO), 2020A = 73 Days

4. Ending Inventory Balance Forecast Example (DIO)
The switch toggle in the top right corner cycles between the two methods to forecast the inventory balance.
- “Turnover” Approach → If the toggle is set to “Turnover”, COGS is divided by the inventory turnover assumption.
- “DIO” Approach → If the switch is set to “DIO”, the days inventory outstanding (DIO) assumption is divided by 365 days and then multiplied by the COGS
On the job, it is far more common to see models that project inventory using the DIO approach (often denoted as “Inventory Days”) than based on turnover days.
However, the projected inventory balances are equivalent under both approaches, as confirmed by our completed model.
From our starting period (2020) to the final year of the forecast (2025), we can see how our company’s inventory balance has increased by $20 million to $26 million.
- Ending Inventory Balance, 2021E = $21 million
- Ending Inventory Balance, 2022E = $22 million
- Ending Inventory Balance, 2023E = $23 million
- Ending Inventory Balance, 2024E = $24 million
- Ending Inventory Balance, 2025E = $26 million

Step-by-Step Online Course
Everything You Need To Master Financial Modeling
Enroll in The Premium Package: Learn Financial Statement Modeling, DCF, M&A, LBO and Comps. The same training program used at top investment banks.
The ultimate guide to DIO
Days Inventory Outstanding (DIO) is an interesting metric. At nVentic, we often use it as a conversation starter – a first outside-in look at how a company is doing in terms of inventory management. The fewer days’ inventory you have, the quicker your cash conversion cycle will be. As such, DIO is a useful component of a balanced supply chain scorecard. But what exactly is DIO and what does it really tell you about a company’s inventory levels?
What is DIO?
Days Inventory Outstanding is the value of inventory held divided by an average day’s cost of sales.
Let’s break that down.
Company A’s balance sheet shows an inventory value of €1 billion. The income statement shows cost of sales of €3.65 billion. This means that an average day’s cost of sales is €10 million (€3.65 billion / 365 days). Which in turn means that the €1 billion inventory is equivalent to 100 days’ cost of sales (€1 billion / €10 million).
If you like formulas, DIO = Inventory value / (Annual cost of sales / 365)
DIO of 100 implies that you have inventory to cover you for 100 days’ average activity, although this is misleading and we will return to what it is really telling you (and what it’s not) below.
The big advantage of DIO is that it is a very simple metric to calculate quickly based on publicly available information. Only privately held firms that do not report their figures, and a relatively small number of firms that do not break down their costs in a way which isolates cost of sales, prevent anyone from calculating DIO for any company. For more detail, and variants on the formula, see the technical notes at the end of this article.
What does DIO tell you?
DIO is a simple metric with which to compare companies, although this only really makes sense when comparing companies in the same or very similar industries. For instance, if you manufacture Scotch Whisky and you allow your product to mature for an average of 10 years before you sell it, there is little point in comparing your DIO with that of a business which buys and sells cut flowers.
If you compare the DIO of two companies in the same industry and with comparable products, then – all other things being equal – the one with a lower DIO is likely to be more efficient. That “all other things being equal” is an important point since differences in DIO can be driven by either structural or performance differences.
The structure of your supply chain is a major driver of DIO. If you have highly variable demand, make to stock and have very long supply lead times, you will need much more inventory than if you have stable demand, make to order and have short lead times. For instance, if your strategy is to source components from the other side of the world while your direct competitors source locally, you will need more inventory than them.
If there are no major structural differences at play, then comparing DIO between companies is indicative of efficiency, and having higher DIO than your main competitors is a strong hint that you have good potential to improve your inventory levels. Although it is also worth saying that, as very few companies are anywhere close to optimising their inventories, having a lower DIO than your competitors is not necessarily a reason for complacency.
What does DIO not tell you?
What DIO cannot do is tell you how much inventory you should have. Optimal inventory levels need to be calculated bottom up, based on the properties of each individual item that you stock. The optimal level will depend on the service level you are targeting, your lead times, the variability in your supply chain and a number of other factors.
If you can calculate your optimal inventory levels bottom up, then you could in principle turn that into a DIO target, although this is not so simple, since any change in inventory is also likely to involve a change in cost of sales. But if you are genuinely in a position where you regularly calculate how much inventory you should hold and compare it with actuals, then you have a much more operationally useful KPI than DIO in place anyway. At nVentic, we have automated the bottom-up calculation of optimum inventory levels.
DIO should not be seen as a proxy for service level. Intuition might seem to tell you that low DIO could indicate a higher risk of shortages, but there is limited data to support this view. Shortages are not caused by not having enough inventory overall, but by not having enough of the right inventory. By definition, if you have a positive DIO, you have not completely run out of inventory. Companies that manage their inventories well have lean inventories and high service levels simultaneously.
And finally, DIO does not actually tell you how much inventory cover you have. In our example, Company A had 100 days inventory outstanding. In a simplistic sense, this implies that they have enough inventory on hand to cover 100 days’ worth of sales. But, of course, they don’t, since DIO is just an average based on value. They actually have more or less than 100 days item by item – in a lot of cases much more or less.
This much probably seems obvious. There is no way you could actually hold exactly 100 days’ worth of sales in inventory unless you had completely uniform and predictable demand. But how much do you think the distribution of days’ inventory typically varies from the mean? Do you have something akin to a bell curve in mind? Let’s have a look at some actual examples of different types and sizes.
What is Days Inventory Outstanding? (DIO)
Days inventory outstanding (DIO) is a working capital management ratio that measures the average number of days that a company holds inventory for before turning it into sales. The lower the figure, the shorter the period that cash is tied up in inventory and the lower the risk that stock will become obsolete. Days inventory outstanding is also known as days sales of inventory (DSI) and days in inventory (DII).
Days inventory outstanding is one component of the cash conversion cycle (CCC), together with days payable outstanding (DPO) and days sales outstanding (DSO). The CCC, which measures how quickly a company converts its investment in inventory into cash, is calculated as:
Cash Conversion Cycle = DIO + DSO – DPO
The CCC can therefore be optimized (reduced) in three different ways: by reducing DIO, reducing DSO or increasing DPO.
Days inventory outstanding formula
Days Inventory Outstanding is usually calculated as follows:
DIO = average inventory/cost of goods sold x number of days
- Average inventory is the average value of inventory – companies may use the value of inventory at the end of a reporting period, or the average value of inventory during the period
- Cost of goods sold is the cost of producing products sold during the period, including the cost of raw materials, labor and utilities
- Number of days is the number of days in the period, i.e. 365 days for a year or 90 days for a quarter
Days inventory outstanding example
For example, if a company has $27,000 in inventory on average during a one-year period, and the cost of goods sold is $243,000, the DIO will be calculated as follows:
DIO = 27,000/243,000 x 365
Inventory turnover ratio
Related to DIO is the inventory turnover ratio, which calculates how many times a company sells and replaces its inventory during a given period of time. Inventory turnover can be calculated as follows:
Inventory turnover = cost of goods sold/average inventory
So for the company in the example above, inventory turnover would be calculated as:
Inventory turnover = 243,000/27,000
DIO can also be calculated as:
DIO = 1/inventory turnover x number of days
So in this example:
What does a high or low days inventory outstanding mean?
Typical DIO can vary considerably between industry sectors. By comparing a company’s DIO with other companies in the same sector, it may be possible to draw some conclusions. What does a high DIO vs a low DIO mean?
High DIO
If a company has a high DIO, it is not converting inventory into sales quickly, and may therefore not be managing inventory effectively compared to others within the sector. If DIO is high, the company’s cash is tied up in inventory for a longer period, meaning it cannot be deployed for other purposes. A high DIO may also be associated with overstocking, leading to higher than necessary storage costs and a high level of obsolete stock that may never be sold.
Low DIO
If a company has a low DIO, it is converting its inventory to sales rapidly – meaning working capital can be deployed for other purposes or used to pay down debt. If the company has a low DIO, there is also less chance that stock will become obsolete and have to be written off. However, a low DIO might also indicate that the company could struggle to meet a sudden increase in demand.
Conclusions can likewise be drawn by looking at how a particular company’s DIO changes over time. For example, a reduction in DIO may indicate that the company is selling inventory more rapidly in the past, whereas a higher DIO indicates that the process has slowed down.
How to improve days inventory outstanding
As a rule of thumb, a lower DIO is seen as more favorable than a higher DIO. DIO can be reduced by speeding up the conversion of inventory into sales, or by reducing the value of inventory held. As such, some strategies that businesses can adopt in order to reduce their DIO include the following:
- Increasing the accuracy of planning and forecasting to address any mismatch between predicted and actual sales. The more accurately you can forecast demand, the less need there will be to keep a higher than necessary level of inventory
- Increasing demand by deploying more effective marketing strategies
- Speeding up the sales process – the faster a sale can be made; the sooner inventory will be converted into cash
- Optimizing stock levels using inventory management techniques such as just-in-time delivery
- Disposing of obsolete or slow-selling inventory, for example by offering discounts or free shipping
That said, a high DIO is not always problematic. Some companies may actively choose to keep higher levels of inventory – for example, if a significant increase in customer demand is expected. Another consideration is that some types of business will see seasonal fluctuations in demand for products, meaning that DIO may vary at different times of the year.
What is Flexible Funding?
Flexible Funding is a feature for Taulia Payables that allows buyer organizations to use the right funding at the right time. It gives corporate treasurers options to meet their short-term cash flow needs without restricting the liquidity suppliers rely on.
What is a working capital funding gap?
A working capital funding gap is the difference between short term assets and short-term liabilities. Learn everything you need to know about funding gaps here.
What is invoice factoring?
The accounts receivable (AR) process is the series of actions businesses carry out to collect their accounts receivable. Learn more about it here.
What is the accounts receivable process/cycle?
The accounts receivable (AR) process is the series of actions businesses carry out to collect their accounts receivable. Learn more about it here.
What is accounts receivable factoring?
Accounts receivable factoring is a way for businesses to secure financing by selling their unpaid invoices for cash. Learn more in our glossary post.
What is debt financing?
Debt financing allows businesses to borrow money to fund their short-term needs. Get a full definition and explanation in our guide to debt finance.
What is working capital funding?
Working capital funding, also known as working capital financing, is a method of business financing. Learn more about the types of working capital funding here.
What is an integrated ERP system?
Integrated ERP systems refers to the combination of an ERP with integrated modules that can help you manage diverse business processes from one platform.
What is a lean supply chain?
Lean supply chains are designed to maximize efficiency. Learn all about the principles of lean supply chain management in our glossary entry.
What is supplier segmentation?
Learn everything you need to know about supplier segmentation, including what supplier segmentation model to use and how to tackle the process, in our guide.
What is ESG?
What is ESG? ESG stands for environmental, social and governance. Together, these three principles form a framework that’s used to measure how sustainably, ethically, and responsibly an organization is acting. ESG is most often used to describe the efforts companies take to mitigate the potential negative outcomes of their operations. It also refers to a…
What is supply chain management?
What is supply chain management? Supply chain management (SCM) describes the process businesses use to manage the flow of goods, data, and payments throughout a supply chain. Effective supply chain management is instrumental in ensuring every element of the supply chain works towards achieving broader business objectives, whether that’s cost-efficiency, resilience, quick order fulfillment, or…
What is supply chain optimization?
What is supply chain optimization? Supply chain optimization is the process of refining the structure and operation of a supply chain. It aims to make the best use of resources and technology to extract greater efficiency and performance from the supply chain network. Well-optimized supply chains enable businesses to meet their broader objectives, whether that’s…
What is accounts receivable?
What is accounts receivable? Accounts receivable (AR) is the term used to describe money owed to a business by its customers for purchases made on credit. It’s listed as a current asset on the balance sheet, representing the total value of outstanding invoices for products or services sold but not yet paid for. Total accounts…
What is cash flow management?
What is cash flow management? Cash flow management is the process of optimizing the flow of money in and out of a business to achieve a specific operational aim. Effective cash flow management enables businesses to use their working capital better and fuel growth or build resilience. It involves using several levers, including the approach…
What is strategic sourcing?
What is strategic sourcing? Strategic sourcing is the term used to describe a strategic approach to the sourcing process. It involves the same fundamental steps – research, analysis, negotiation, contracting, and onboarding of new suppliers to fulfill demand for goods or services – but is oriented to contribute to broader business objectives. It also often…
What is automated spend analysis?
What is automated spend analysis? Automated spend analysis is an automatic digital process that captures, consolidates, and interprets spend data across an organization. It’s used to provide insights into spend efficiency and effectiveness, informing sourcing and purchasing decisions. It’s typically facilitated through dedicated automated spend analysis software, usually integrated with a wider enterprise resource planning…
What is the new FASB accounting treatment for supply chain finance?
What is the new FASB accounting treatment for supply chain finance? In September 2022, the Financial Accounting Standards Board (FASB) — the governing body for accounting standards in the United States — updated its standards to include a requirement for SCF disclosure on company financial statements. For most organizations, disclosure of an existing SCF program…
What is spend visibility?
What is spend visibility? Spend visibility refers to how well a company can understand and track how, where, and why capital is used in their business operations. Spend visibility increases when finance teams can more accurately see where company money is being spent. Low spend visibility is defined by difficulties tracking spend comprehensively or accurately….
What is 2/10 net 30?
What is 2/10 net 30? 2/10 net 30 is a trade credit often offered by suppliers to buyers. It represents an agreement that the buyer will receive a 2% discount on the net invoice amount if they pay within 10 days. Otherwise, the full invoice amount is due within 30 days. It’s one of the…
What is working capital ratio?
What is working capital ratio? Working capital ratio is a measurement that shows a business’s current assets as a proportion of its liabilities. It’s a metric that provides an overview of financial health and liquidity, indicating whether current liabilities can be paid by existing assets. In the case of working capital ratio, assets are typically…
What is a virtual card?
What is a virtual card? A virtual card is a payment method that is virtual rather than physical. It functions similarly to a traditional credit card but takes the form of a single-use 16-digit number and three-digit CVV code generated online, instead of a plastic or metal card that is received through the post. Virtual…
What is e-procurement?
What is e-procurement? E-procurement refers to the set of digital processes that dictate B2B buyer-supplier relationships in the supply chain. Utilizing technology, e-procurement aims to centralize the workflows involved in purchasing goods or services and bring about efficiency improvements. It’s essentially the digitization of the standard procurement process. E-procurement, short for electronic procurement, replaces traditional…
What is source-to-pay?
What is source-to-pay? Source-to-pay (or S2P) is the process that outlines how organizations fulfill their sourcing and procurement needs. It begins with the identification of demand for a product or service, encompasses steps including supplier selection, contract management, and requisition, and ends with a payment being made. It can be split into two composite sections:…
What is supplier relationship management?
What is supplier relationship management? Supplier relationship management is the set of processes that organizations use to build, manage, and maintain relationships with their suppliers, or vendors. A supplier relationship management strategy is essential to ensure that relationships are built productively, with a view to increasing the overall effectiveness and resilience of the supply chain….
What is supplier information management?
What is supplier information management? Supplier information management (SIM) refers to the set of processes or the system that organizations use to collect, store, access, and update important data about their suppliers. From contact details to contractual documentation, the data involved in supplier information management is essential in the broader process of vendor management. A…
What is AP automation?
What is AP automation? AP automation, short for accounts payable automation, is the use of software to automate part or all of the accounts payable process. It aims to create efficiency in the accounts payable workflow by digitizing how vendor invoices are received, processed, and stored. In removing manual processes and the need for paper-based…
What is accounts payable?
What is accounts payable? Accounts payable (AP) represents the amount that a company owes to its creditors and suppliers (also referred to as a current liability account). Accounts payable is recorded on the balance sheet under current liabilities. When a business purchases goods or services from a supplier on credit, payment isn’t made straight away,…
What is accounts receivable (AR) financing?
What is accounts receivable (AR) financing? Accounts receivable or AR financing is a type of financing arrangement which is based on a company receiving financing capital in return for a chosen portion of its accounts receivable. An AR financing arrangement can be structured in several ways, including as an asset sale or a loan. Essentially,…
What is the cash conversion cycle (CCC)?
What is the cash conversion cycle (CCC)? The cash conversion cycle (CCC) – also known as the cash cycle – is a metric expressing how many days it takes a company to convert the cash it spends on inventory back into cash by selling its product. The shorter a company’s CCC, the less time it…
What is cash flow forecasting?
What is cash flow forecasting? Cash flow forecasting, also known as cash forecasting, estimates the expected flow of cash coming in and out of your business, across all areas, over a given period of time. A short-term cash forecast may cover the next 30 days and can be used to identify any funding needs or…
What is Days Inventory Outstanding? (DIO)
What is Days Inventory Outstanding? (DIO) Days inventory outstanding (DIO) is a working capital management ratio that measures the average number of days that a company holds inventory for before turning it into sales. The lower the figure, the shorter the period that cash is tied up in inventory and the lower the risk that…
What is Days Payable Outstanding? (DPO)
What is Days Payable Outstanding? (DPO) Days payable outstanding (DPO) is a useful working capital ratio used in finance departments that measures how many days, on average, it takes a company to pay its suppliers. As such, DPO is an important consideration when it comes to managing a company’s accounts payable – in other words,…
What is Days Sales Outstanding? (DSO)
What is Days Sales Outstanding? (DSO) Days sales outstanding (DSO) is a working capital ratio which measures the number of days that a company takes, on average, to collect its accounts receivable. The shorter the DSO, the faster the company collects payment from its customers – and the sooner it is able to make use…
What is dynamic discounting?
What is dynamic discounting? Dynamic discounting is a solution that provides suppliers with the option of receiving early payment in exchange for a discount on their invoice. As a result, suppliers can typically access lower cost funding than they might otherwise receive, while harnessing working capital in order to invest in growth and innovation. Buyers, meanwhile,…
What is an early payment discount?
What is an early payment discount? An early payment discount is a form of trade finance, allowing buyers to pay a discounted amount to suppliers in exchange for settling invoices before their maturity date. Also known as a prompt payment discount or early settlement discount, it’s typically calculated as a percentage of the goods and…
What is inventory management?
What is inventory management? Inventory management is a systematic approach to sourcing, storing, and selling inventory. Effective inventory management involves optimizing the flow of goods within an organization, from purchase right through to sale, always ensuring that an appropriate quantity is available in the right place and at the right time to meet customer demand. Inventory in…
What is invoice processing?
What is invoice processing? Invoice processing is a business function that involves managing incoming invoices from initial receipt through to payment. It’s carried out by the accounts payable department and is a critical component of the procure-to-pay process as the final step of any procurement activity. The invoice processing cycle is made up of several composite…
What is inventory cycle time?
What is inventory cycle time? Inventory cycle time is the amount of time it takes to produce and deliver an order from a customer, usually measured in days. It essentially measures the speed at which a company can complete the manufacturing or assembly process from start to end, turning raw materials or components into a…
What is procure-to-pay? (P2P)
What is procure-to-pay? (P2P) Procure-to-pay is a term that encompasses the processes which take place when a company purchases, receives and pays for goods and services. The activities that make up the procure-to-pay process range from identifying the initial need for procurement of goods or services to the final steps of approving invoices and paying…
What Is The Procurement Life Cycle?
What is the procurement life cycle? The procurement cycle is the process businesses use to find and obtain goods. It involves multiple steps, including identifying the need for a good or service, finding the right supplier, negotiating terms, creating a purchase order, and receiving the delivery. It’s also known as the procurement life cycle or,…
What is receivables finance?
What is receivables finance? Receivables finance, or receivables financing, is a trade finance method businesses can use to receive funding matching the amounts owed to it by its customers in outstanding invoices. These amounts are known as trade receivables or accounts receivable. By financing its receivables, a business can receive payments earlier, meaning it can…
What is reverse factoring?
What is reverse factoring? Reverse factoring is a type of supplier finance solution that companies can use to offer early payments to their suppliers based on approved invoices. Suppliers participating in a reverse factoring program can request early payment on invoices from the bank or other finance provider, with the buyer sending payment to the…
What is trade finance?
What is trade finance? Trade finance is the term used to describe the tools, techniques, and instruments that facilitate trade and protect both buyers and sellers from trade-related risks. The purpose of trade finance is to make it easier for businesses to transact with each other. It also helps to reduce the risks involved in…
What are trade receivables?
What are trade receivables? Trade receivables are defined as the amount owed to a business by its customers following the sale of products or services on credit. Also known as accounts receivable, trade receivables are classified as current assets on the balance sheet. Most companies allow their customers to use credit on purchases of goods…
What is strategic procurement?
What is strategic procurement? Strategic procurement, or procurement strategy, is the process businesses use to acquire goods or services of the right quality, at the right price, and in time to meet customer demand. It brings procurement activities in-line with a company’s broader objectives, while also reducing supply chain risk. Strategic procurement is a long-term, organization-wide…
What is supply chain finance?
What is supply chain finance? Supply chain finance, also known as supplier finance or reverse factoring, is a financing solution in which suppliers can receive early payment on their invoices. Supply chain finance reduces the risk of supply chain disruption and enables both buyers and suppliers to optimize their working capital. Unlike other receivables finance…
What is vendor management?
What is vendor management? Vendor management is a term that describes the processes organizations use to manage their suppliers, who are also known as vendors. Vendor management includes activities such as selecting vendors, negotiating contracts, controlling costs, reducing vendor-related risks and ensuring service delivery. The vendors used by a company will vary considerably depending on…
What is working capital management?
What is working capital management? Working capital management is a business process that helps companies make effective use of their current assets and optimize cash flow. It’s oriented around ensuring short-term financial obligations and expenses can be met, while also contributing towards longer-term business objectives. The goal of working capital management is to maximize operational…
Days Inventory Outstanding
Over 1.8 million professionals use CFI to learn accounting, financial analysis, modeling and more. Start with a free account to explore 20+ always-free courses and hundreds of finance templates and cheat sheets.
Written by CFI Team
What is Days Inventory Outstanding (DIO)?
Days inventory outstanding (DIO) is the average number of days that a company holds its inventory before selling it. The days inventory outstanding calculation shows how quickly a company can turn inventory into cash. It is a liquidity metric and also an indicator of a company’s operational and financial efficiency. Days inventory outstanding is also known as “inventory days of supply,” “days in inventory,” or “the inventory period.”
Days Inventory Outstanding Formula
The formula for days inventory outstanding is as follows:
Days Inventory Outstanding = (Average inventory / Cost of sales) x Number of days in period
- Average inventory = (Beginning inventory + Ending inventory) / 2
- Cost of Sales is also known as Costs of Goods Sold
- Days in Period means the number of days in the period, such as an accounting period, that is being examined – the period may be any time frame – a week, a quarter, or annually
Example of Days Inventory Outstanding
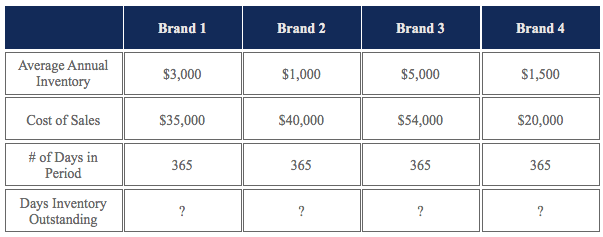
Company A sells several brands of furniture. The manager would like to determine which brands are doing well in terms of inventory turnover. He’s tasked you with determining the days inventory outstanding for several different brands:
To determine the DIO of each brand:
- DIO Brand 1: ($3,000 / $35,000) x 365 = 31.29 days
- DIO Brand 2: ($1,000 / $40,000) x 365 = 9.13 days
- DIO Brand 3: ($5,000 / $54,000) x 365 = 33.80 days
- DIO Brand 4: ($1,500 / $20,000) x 365 = 27.38 days
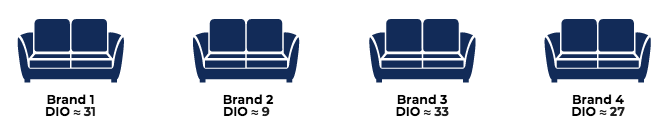
From determining the DIO of each brand, you can easily see which brands are doing well relative to other brands. In this case, Brand 2 is doing extremely well, while Brands 1,3, and 4 are all lagging about equally behind. The manager may then meet with the sales and marketing team to try to figure out how to improve sales of those brands. The company might consider dropping Brand 3, the poorest performer, entirely.
Download the Free Template
Enter your name and email in the form below and download the free template now!
Days Inventory Outstanding Template
Download the free Excel template now to advance your finance knowledge!
Interpretation of Days Inventory Outstanding
A low days inventory outstanding indicates that a company is able to more quickly turn its inventory into sales. Therefore, a low DIO translates to an efficient business in terms of inventory management and sales performance.
A high days inventory outstanding indicates that a company is not able to quickly turn its inventory into sales. This can be due to poor sales performance or the purchase of too much inventory. Having too much idle inventory is detrimental to a company as inventory may eventually become obsolete and unsellable. Holding excess inventory also negatively impacts cash flow.
In financial analysis, it is important to compare DIO with the DIO of similar companies within the same industry. For example, companies in the food industry generally have a DIO of around 6, while companies operating in the steel industry have an average DIO of 50. Therefore, comparing DIO between companies in the same industry offers a much better, more accurate and fair, basis for comparison.
Importance of Days Inventory Outstanding
- DIO is a measure of inventory management effectiveness and is used by management to determine how long the company’s stock of inventory typically lasts – how long it takes to convert existing inventory to sales/cash.
- DIO shows the liquidity of inventory. A short DIO means inventory is converted to cash more quickly while a high DIO shows poor inventory liquidity.
- DIO should never be compared across industries, as the DIO varies greatly between industries.
- A lower DIO is generally more favorable than a high DIO.
More Resources
Thank you for reading CFI’s guide to Days Inventory Outstanding. To keep learning and advancing your career, the following CFI resources will be helpful:
- Days Deduction Outstanding (DDO)
- Day Sales Outstanding
- Days Inventory Outstanding Template
- Financial Accounting Theory
- See all accounting resources
- Share this article